 Zwischen
Anthropic booked the hall. The guests didn't RSVP.
Costs locked in for years, customers who can leave, charts that flatter and a stock bill still to land. What Anthropic's S-1 says once you read past the highlights.
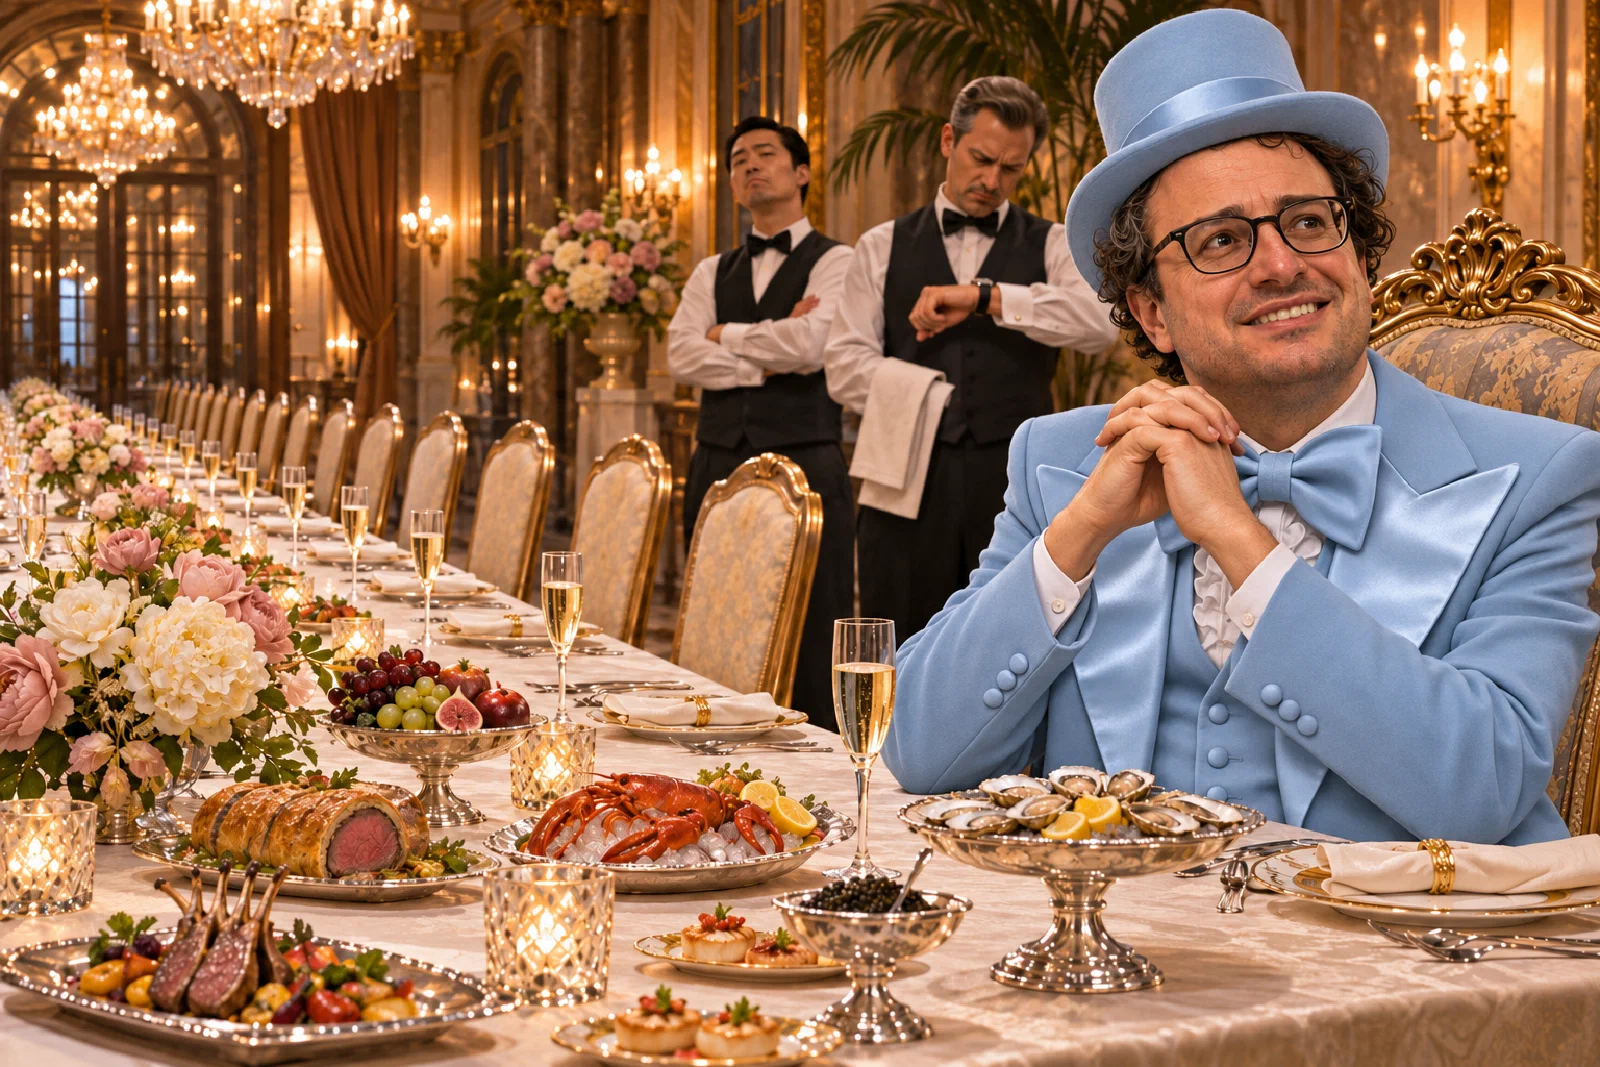
On October 15, some of Anthropic’s existing and prospective investors were talking about $1.5 trillion instead of roughly $2 trillion. Revenue had grown 45% in one quarter, and that was the disappointment (‘Investors temper Anthropic IPO valuation expectations over revenue growth slowdown’, Reuters, October 15, 2026).
Eleven days later the S-1 went public and AI stocks rallied, though Reuters’ own commentary noted the filing added little to numbers already circulating (‘Morning Bid’, Reuters, October 27, 2026).
That isn’t a reversal. Different people were answering different questions, and neither mood changed a dollar of what Anthropic owes. What it owes is the interesting part.
Anthropic may well be an exceptional company. Its filing still describes a business whose costs are mostly fixed and whose revenue is mostly revocable, and both $1.5 trillion and $2 trillion assume the revenue keeps showing up.
Who signed what
The supplier commitments aren’t one number. They come in four grades.
Some are hard. Anthropic owes Amazon, Google and Microsoft about $270 billion through as late as 2036, in each case “regardless of actual usage.” Broadcom equipment leases add about $161 billion and can’t be cancelled except on default (‘Anthropic S-1’, SEC, October 26, 2026).
Some are paid on delivery. Lambda and Nscale get paid once capacity is delivered and accepted, which protects Anthropic if a data center is late, but not if demand is.
Some are estimates. Anthropic expects another $125 to $150 billion in TPU payments outside its commitments table, because capacity and pricing aren’t set yet.
And one has an exit. SpaceX is up to $120.5 billion into 2029, but after early 2027 either side can leave on 90 days’ notice.
Since June 30, Anthropic has signed or amended deals carrying another $245 billion of future minimum payments, some of them conditional.
The customers, in Anthropic’s words:
“Many of our top customers are not subject to long-term contracts with us or have contracts with near-term expiration dates and are able to reduce or in some cases cease spending at any time and for any reason.”
At the end of June, everything customers had contractually committed to, across all future periods, came to $10.8 billion. Anthropic booked $11.6 billion in that one quarter. That isn’t a coverage ratio, because backlog doesn’t count customers who simply keep buying, and plenty do.
How sturdy is the habit?
Two disclosures deserve more attention.
The first: Anthropic estimates that 5% to 7% of its revenue in the first nine months of 2026 came from customers it later determined were violating its usage policy or commercial terms. Using the third-quarter revenue Reuters reported, that’s roughly $2 billion. Anthropic books the revenue, then restricts or cuts off the customer once it catches them. It tightened enforcement in August and September and expects that share to fall, with the effect on growth “uncertain.”
Nobody is alleging improper accounting, and we can’t tell you how much of that demand compliant customers will replace. At $1.5 trillion, it’s valued like every other dollar.
The second: model versions released in the prior six months accounted for over 80% of third-quarter revenue. Anthropic presents this as customers adopting new capability, and it probably is. It also means the revenue gets re-earned with every release, against costs locked in for years.
“Compute efficiency”
The filing’s best chart is titled “Significant increase in revenue per dollar of compute.” It climbs from 0.40x in early 2025 to 2.08x in the second quarter of 2026, and the callout calls that a 5.2x increase in “compute efficiency.”
The text around it says Anthropic buys compute 12 to 18 months ahead, that the expense is generally fixed in the near term, and that it rose as committed capacity arrived “rather than in response to in-period demand.” In the second quarter, revenue grew 144% quarter over quarter while compute grew 65%.
Some of that may well be real efficiency. But Anthropic has been compute-constrained, and a company running flat out on capacity it already paid for will look remarkably efficient. The test comes when the next wave of committed capacity lands, and the chart stops at June.
45 times the code. Now what?
The filing says the efficiency runs through the whole company. Over 90% of contributions to the codebase in September were written by Claude. Daily code volume per engineer is over 45 times its 2024 average. Trailing revenue per employee is over $6.6 million.
This is our beat, so forgive us. Code volume is the dashboard nobody asked what to do with. A model with no stopping rule will happily produce 45 times the code, and the number says nothing about what that code costs to review and maintain, or whether it needed to exist. Nothing here suggests the figures are false.
Revenue per employee has a denominator problem too. Anthropic’s revenue is produced mainly by compute, not its 5,300 employees, and the second quarter’s compute bill annualizes to about $4 million per employee. To know whether the machine is efficient, ask what’s left after paying for it.
The cost that hasn’t arrived
The margin chart is titled “Operating efficiency drives margin expansion” and shows adjusted operating margin reaching 19%. GAAP operating margin that quarter was 8%. The gap is mostly stock compensation, and it’s about to get much bigger.
Most of Anthropic’s RSUs vest only when it goes public, so at the end of June, $26.6 billion of that cost hadn’t touched the income statement. Another $5.8 billion in grants was approved after that. A new equity plan reserves up to 2.95 billion shares, with annual increases. Reserved isn’t issued, and without a price nobody can finish the per-share math.
When growth disappoints
This is where we stop reporting and start guessing.
Our suspicion is that if growth disappoints for long enough, these obligations get renegotiated. The S-1 doesn’t say that. It does show the financing getting worse exactly when you’d need it.
Anthropic can use up to $42 billion of Broadcom-linked notes to pay its equipment rent. Those notes carry 9% interest and convert at 90% of the share price. Issued while certain revenue conditions are missed, they carry 13% and convert at 85%. Miss for a sustained period and the right to issue them ends. Anthropic says the thresholds sit well below its actual growth.
In that world, the capacity is still coming, the money for it costs more, and more of the bill gets paid in stock. A renegotiation with Amazon or Google, who are suppliers, financiers and major shareholders at once, wouldn’t look like a default either. It’d look like a longer term, a new tranche, a better conversion price. Class A holders would read about it afterward.
Who you’d complain to
They couldn’t do much about it. A single Class F share, held by an LLC of the seven co-founders, carries 50.1% of the general vote. A trust holding Class T stock generally elects and removes a majority of the board. As a public benefit corporation, Anthropic’s directors also answer to its stated purpose, not just its stockholders.
We don’t think the trust is a sham. Our inference is narrower: the capacity bet is the whole investment, and the public shareholder has unusually little say over it. You’re underwriting the judgment of people who can’t be voted out.
Two things we checked and won’t scream about
Anthropic books marketplace sales gross and records the cloud platforms’ cut, which Reuters put at about 16% of marketplace sales in 2025, as a marketing expense. It says it acts as principal, which is a real position, not a trick. Net presentation wouldn’t change operating profit, though it would move the multiple at $1.5 trillion by about two turns (‘Anthropic IPO prospectus lays bare deep dependence on Big Tech partners’, Reuters, September 29, 2026).
First-half operating cash flow was a positive $3.9 billion, about $1.2 billion of it from working-capital timing. No collections failure has been established. Anthropic just doesn’t treat that as the steady state: it expects “significant net cash used in operating and investing activities for the foreseeable future.”
The evidence against us, all from the S-1:
- There’s a lot of cash. About $131.7 billion in cash and short-term investments at June 30, before any IPO proceeds. This is not a near-term solvency story.
- Concentration is falling. 79% of third-quarter revenue came from outside the top five customers, up from about 64% in the first quarter. No customer accounted for more than 10% of revenue in the first nine months of 2026.
- Commitments are growing. “A growing number” of customers sign non-cancelable minimums, and customers paying $100,000 or more over the trailing 12 months topped 11,900 by September 30.
- The constraint argues for pre-buying. Demand for compute has historically exceeded supply, which is exactly when buying early looks smart.
The next question
Claude works. The revenue is impressive. Neither settles the investor’s question.
How much usage has to show up, at what margin and by when, for each tranche of committed capacity to earn a return for Class A shareholders? The filing is candid about what happens if it doesn’t. The payment calendar is still blank. The amendment will fill it in, along with the price.
That’s the investor’s side. We wanted the facts on the table first. Next, we’ll take the question for companies building on AI: what changes day to day if the hall fills up, and what changes if it stays half empty?
Anthropic has promised to pay. Its customers mostly haven’t.